David Porter is the pioneer of creating community with Next-Gen Residential and Retail Dining crafted through the lens of SOCIAL ARCHITECTURE™ and Abundance Thinking for campus dining programs.
Trellis Strategies surveyed more than 65,000 students at two-year and four-year institutions for its most recent Student Financial Wellness Survey. Three numbers from it belong on the desk of everyone who designs a meal plan.
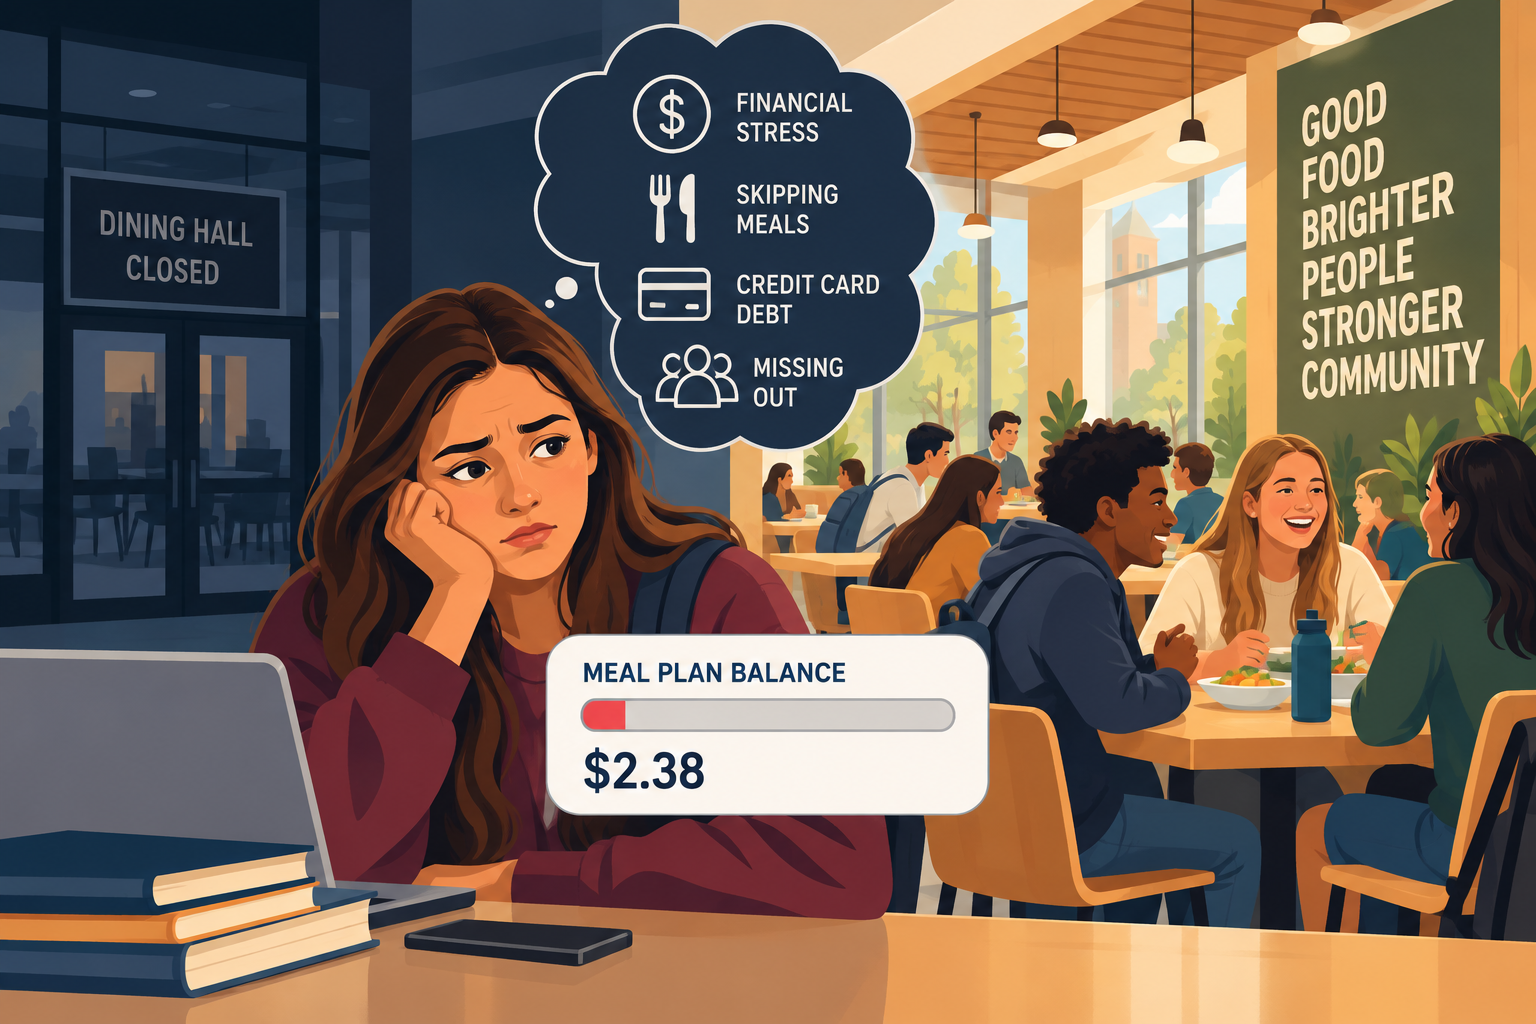
Sixty-five percent of students had run out of money at least once since the start of the year. Fifty-four percent said they would struggle to come up with $500 for an unexpected expense. More than half reported at least one form of basic needs insecurity. Twenty-eight percent had used buy-now-pay-later services, and 13 percent had borrowed through payday or auto title loans.
A Trellis researcher summed it up in one sentence: “a lot of students are living on the edge.”
Now hold those numbers next to the plan design the campus dining industry is adopting fastest. It is called dining dollars, or flex points, or a declining balance, and it works like a debit card: a sum loaded in August, spent at retail prices, gone when it is gone. This fall, campuses from coast to coast have shifted weight from meal swipes toward dollars, in some cases cutting the number of locations where a swipe works at all. The stated reasons are sincere: flexibility, choice, unused swipes.
Here is the question nobody in the plan meeting is asking. For a student who has already run out of money once this year, what is a declining balance except a second account to overdraw?
The Mid-Semester Problem
Every dining director knows the shape of it. Dining dollars are spent fastest in the first six weeks, when everything is new and the balance looks large. By mid-semester the number on the screen has gotten small, and on many campuses a meaningful share of students spend the back half of the semester either rationing their own meals or spending money they do not have to make it to the end of the term. The plan did not run out of food. It ran out of currency.
Then look at what a student with no balance does. They skip lunch. They buy the cheapest calories in the market. They put dinner on a credit card they are struggling to pay off, or on the buy-now-pay-later app, the survey says more than a quarter of their classmates already use. Their family covers the gap if they can. If they cannot, they are hungry on a campus where he or she holds a paid meal plan.
I have described the cascade for years. A mediocre or failing program sends students off campus for food, the extra dollars are financed by family or by financial aid, frustration compounds, and by spring comes the financial recalibration, when the student and their parents conclude the housing and food money is better spent off campus. The declining balance accelerates every step, because it builds the running-out into the design.
Breakage Is Not a Feature
The industry has a word for the money students do not spend: breakage. On a declining-balance plan, unspent dollars at the end of the term are revenue. On a swipe plan, unused meals are revenue. Plans are often priced with that revenue in mind, which means the campus does better financially when students eat less than they paid for.
I wrote in The Porter Principles that this is the only business model in America that begs you to buy down. Most parents do not want to buy down. They want the biggest plan on the menu, as an expression of love, because it promises to take care of their son or daughter. A plan that quietly profits when the student eats less betrays that purchase, and the Trellis numbers tell you which students it betrays first: the 54 percent who cannot find $500, and the more than half who are already insecure in at least one basic need.
I am not an economist, and this is not a personal finance column. It is a design question, and design is what we do.
What Cannot Run Out
The alternative is not complicated. An all-access residential plan, honestly delivered, is the one item on a student’s bill that cannot be overdrawn. It does not care what day of the semester it is. It does not meter her. The student who ran out of money by mid-semester eats the same dinner in the last week of the semester as the student whose parents wire cash every week, at the same table, with no visible difference between them. That is not only good policy for food security. It is the SOCIAL ARCHITECTURE™ of the room: when nobody’s balance is showing, everybody belongs.
Honestly delivered is the condition. An all-access plan attached to a cafeteria operating system, with limited hours, gaps between meal periods, no late night, and stations that run out before the posted close, is a promise the room does not keep, and students will buy around it. Abundance Thinking is what makes the promise real: hours built around the Student Clock, Predictable Abundance so the good stuff is still there at 8:45 pm, and table configurations that invite joining.
Voluntary participation is the purest measure of value. If your residential commons holds roughly 70 percent meal plan participation without equivalencies, swipes, or exchanges in retail propping up the count, you have a Social Coliseum. You also have a campus where the mid-semester problem does not exist.
Our mini documentary, SOCIAL ARCHITECTURE™: The Missing Ingredient, directed by Emmy Award-winning filmmaker Nick Nanton, was filmed on four campuses across two countries. The voices are first-year students describing what it feels like when a campus engineers belonging instead of leaving it to chance. Watch the mini documentary. Not one of them is checking a balance.
Three Questions for the Plan Meeting
The 2027-28 meal plans are being designed right now on most campuses. Before the structure is set, ask three things.
First, pull the dining dollar balances by week for last fall. On what date did the median first-year student’s balance fall below the cost of one more week of meals? That date is the day your plan started sending students to credit cards.
Second, ask what the plan is designed to do when a student runs out. If the honest answer is “nothing,” then the plan was designed for the 35 percent who never run out of money, and the survey says that is the minority.
Third, ask who benefits from breakage, and whether you would be comfortable explaining the answer to the parents who bought the biggest plan as an expression of love.
Two-thirds of students ran out of money this year. The campus cannot fix a student’s bank account. It can decide whether the meal plan is one more thing that runs out, or the one thing that does not. That is not only solvable; it is also preventable, and the design is already in your hands.